The pack a lender reads.
A sample of the kind of work a Solon mandate produces, built on a fictional borrower, Northstar Components, for a £14.6m refinancing and growth facility. One integrated model sits behind every figure. Every page is laid out below; the PDFs are there to take.
Preparing for a financing? Discuss the pack your business needs.
Which document does what, and when?
The pack, side by side.
| Document | What it is for | Who reads it | When in a raise | How it relates |
|---|---|---|---|---|
| One-pager | Deciding whether the rest is opened | The lender’s deal team | First, before the IM | The credit on one page, drawn from the model |
| Information memorandum | Anticipating the lender’s questions | The lender’s deal team, then its credit officer | Under NDA, before anyone meets | The written case, with the model’s exhibits set into the page |
| Lender deck | Presenting the credit and framing the questions | The lender’s deal team, then its committee | At the management meetings | The IM’s credit in slides |
| Credit memorandum | The case in the lender’s own format | The lender’s deal team, for its committee paper | Before the deal team writes its paper | Distils the IM, the deck and the model |
| Debt model | Testing cash and covenants | The credit officer, who runs a downside on it | From the IM onward, reworked by the lender’s analyst | The source of every number in the other four |
At a lender, the deal team originates and sponsors a deal, the credit officer tests it and the credit committee approves it.
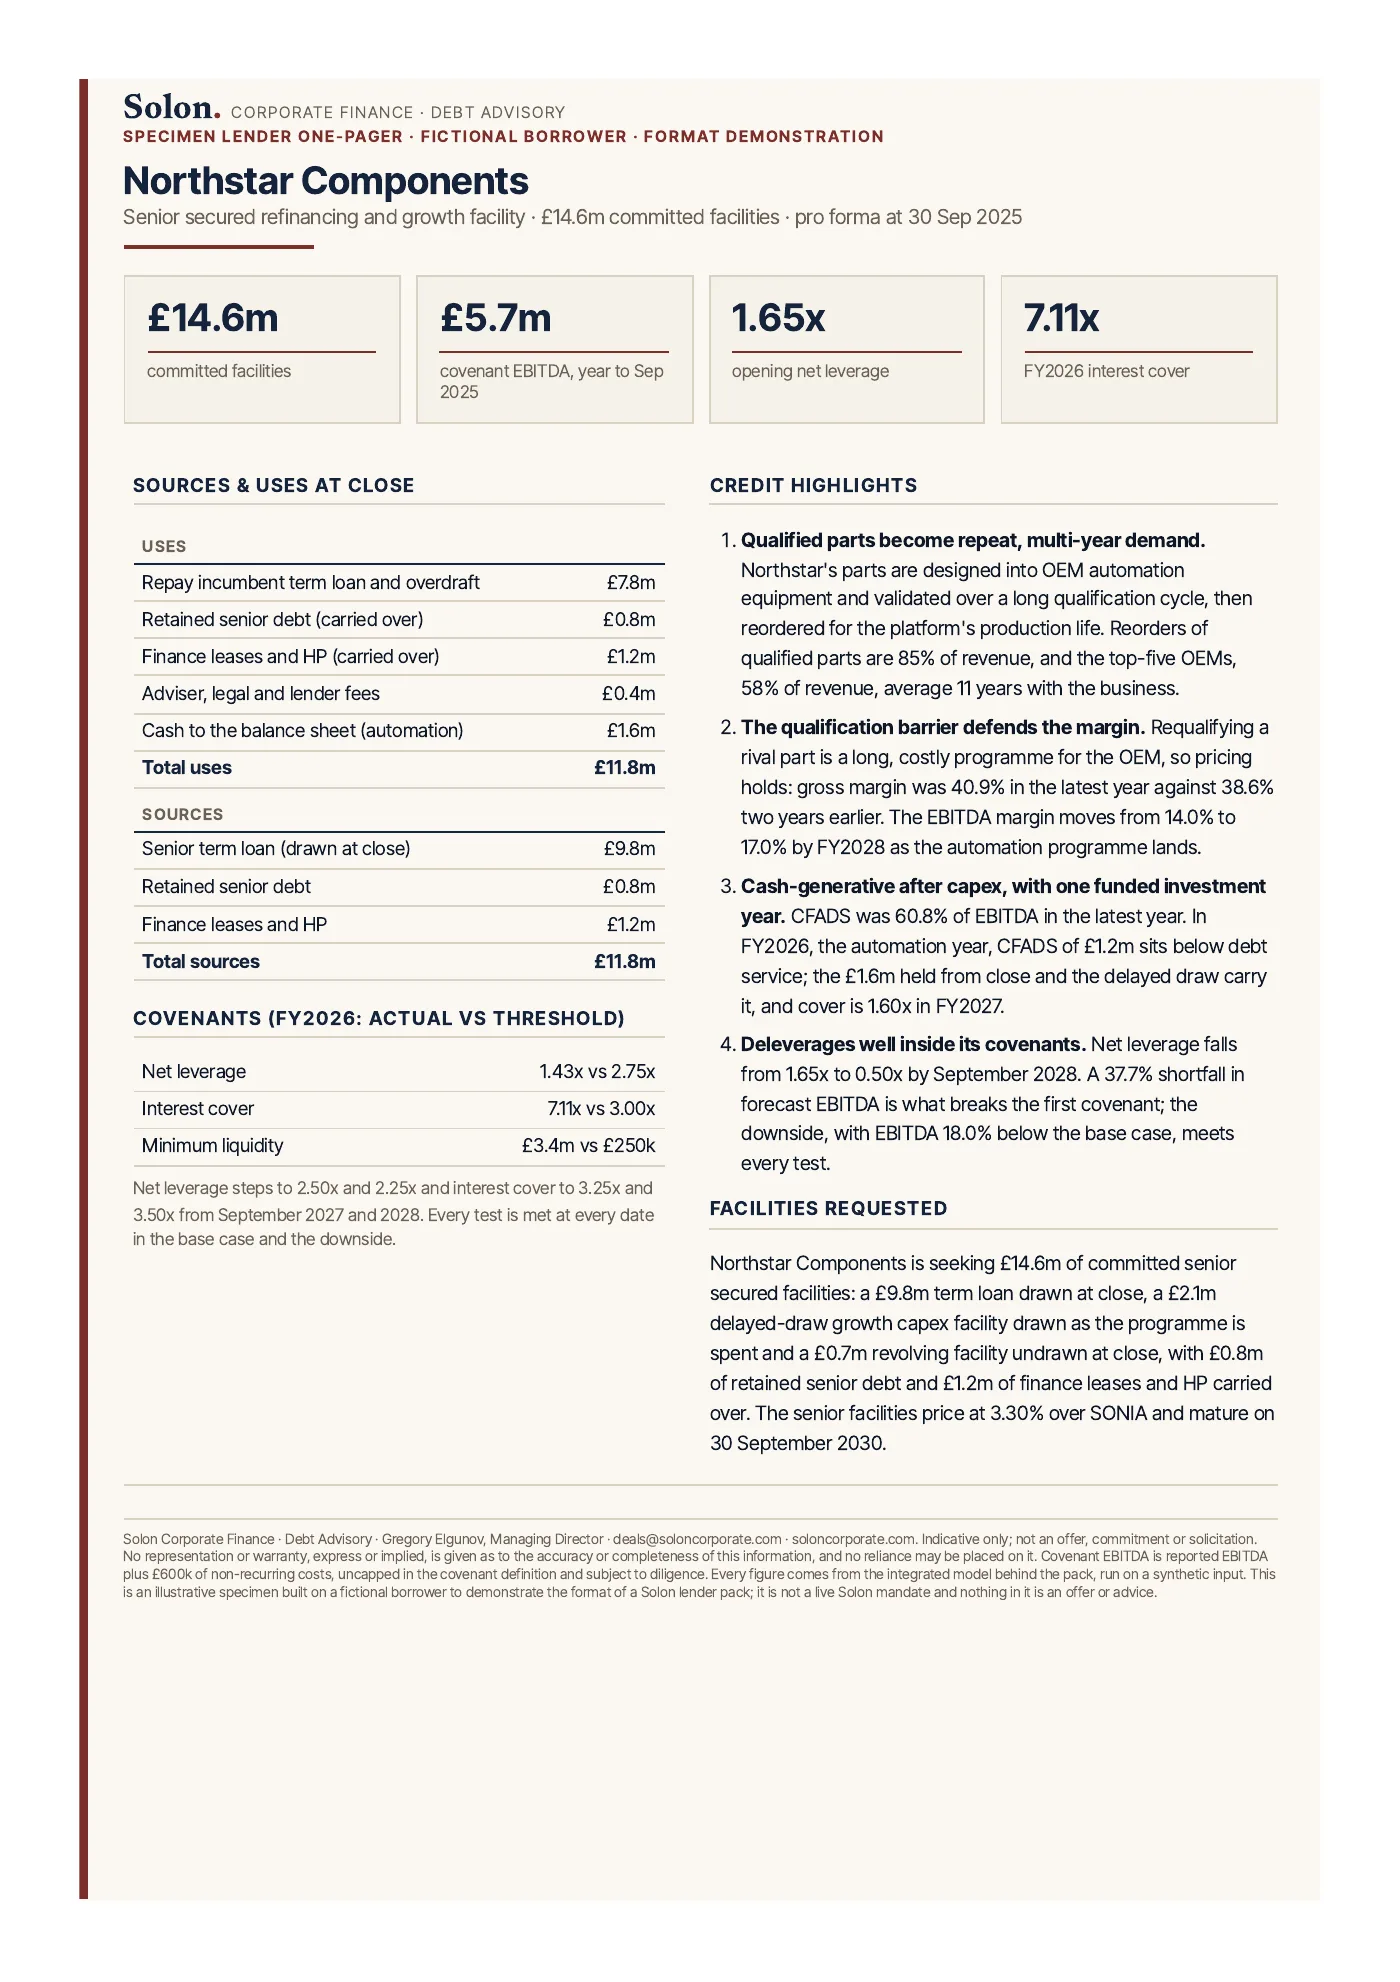
Can the credit be understood on one page?
A single page carrying sources and uses, opening leverage and cover, covenant headroom against the thresholds and the credit highlights.
Want this for your own business? Solon prepares this pack for the borrower, and the first conversation is confidential.
Discuss a pack for your businessHow does the credit present in the room?
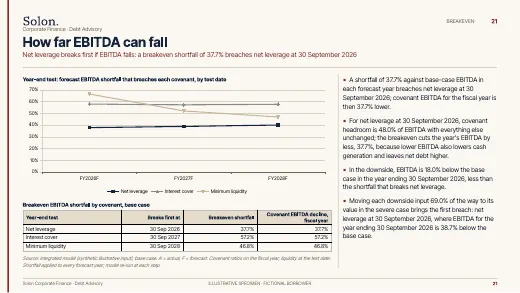
The same credit told in slides, every figure from the integrated model behind the pack. It covers the transaction, the capital structure and key terms, the business and its market, operations, the growth programme and management, three years of trading and the forecast, then the credit analysis: debt service, covenant headroom, how far EBITDA can fall before a covenant breaks, liquidity, the scenarios, what drives the downside and where the first breach falls.
p. 1 of 30
Want this for your own business? Solon prepares this pack for the borrower, and the first conversation is confidential.
Discuss a pack for your businessDoes the case hold when it is read cold?
The document a lender forms its credit view from. The transaction, the capital structure and key terms; the business, its customers and market, operations, the growth programme and management; the financials, quality of earnings and cash conversion; then debt service, covenant headroom, the breakeven, liquidity, the scenarios, the downside bridge and the first breach, with the model's exhibits set into the page.
p. 1 of 27
Want this for your own business? Solon prepares this pack for the borrower, and the first conversation is confidential.
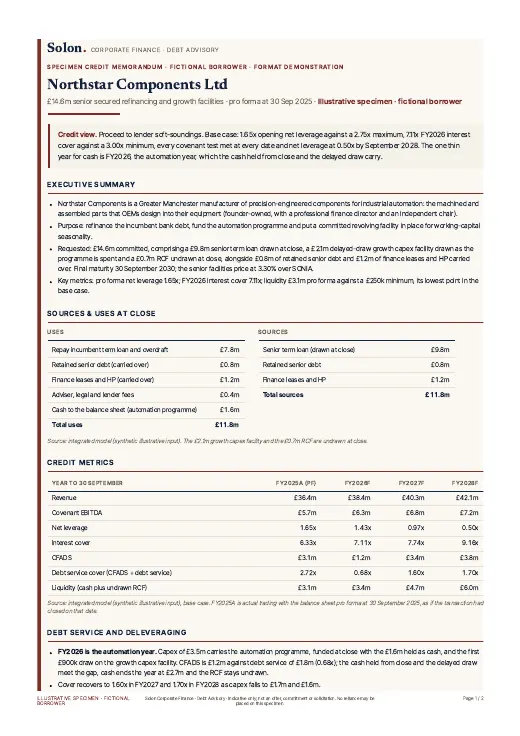
Discuss a pack for your businessWhat would the credit paper say?
The fuller credit view, set out as an executive summary, sources and uses, forecast metrics, debt service and deleveraging, the covenant-EBITDA bridge, covenant headroom, downside scenarios and a risk register with mitigants.
p. 1 of 2
Want this for your own business? Solon prepares this pack for the borrower, and the first conversation is confidential.
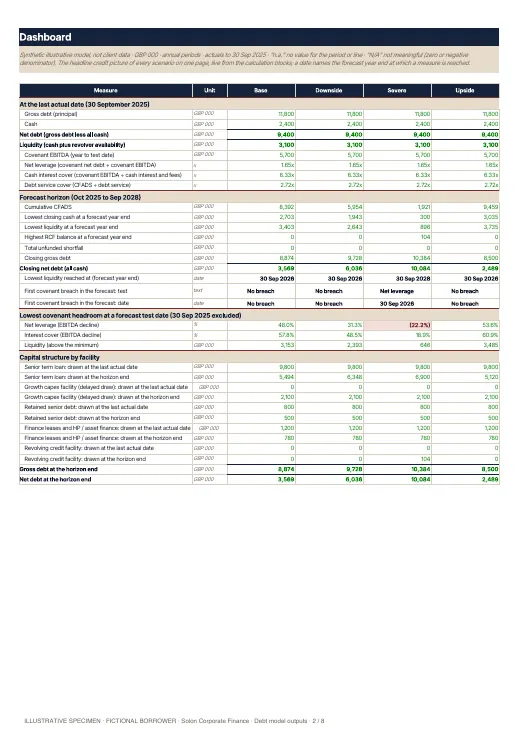
Discuss a pack for your businessDo the numbers reconcile?
The outputs of the integrated model behind the pack, which links trading, working capital, tax, the facility schedules, the cash waterfall and the three statements across four scenarios: the dashboard, credit statistics at each test date, the debt schedules and covenant compliance, the covenant levels, the scenario comparison and the charts.
p. 1 of 8
Want this for your own business? Solon prepares this pack for the borrower, and the first conversation is confidential.
Discuss a pack for your businessWhat is the market these documents are written into?
Solon's count of the UK refinancing wall: 83,957 companies scored against the Companies House charge register, 26,383 carrying a dated facility signal and more than 14,500 inside an estimated window now, with the vintage, lender and holder concentration behind them. Charted aggregates and method; no row-level data.
p. 1 of 6
If your own facility matures in this window, Solon can read your position before the refinancing starts, and the first conversation is confidential.
Discuss your refinancingEvery mandate is prepared to the standard of the documents above; what a particular mandate produces is agreed at engagement. If a financing is in front of you, an early and confidential conversation costs nothing and commits you to nothing.
Put your own numbers to it